August 24, 2026 · Buyer & Seller Tips
Home Appraisals in Dayton Ohio: What Buyers and Sellers Need to Know
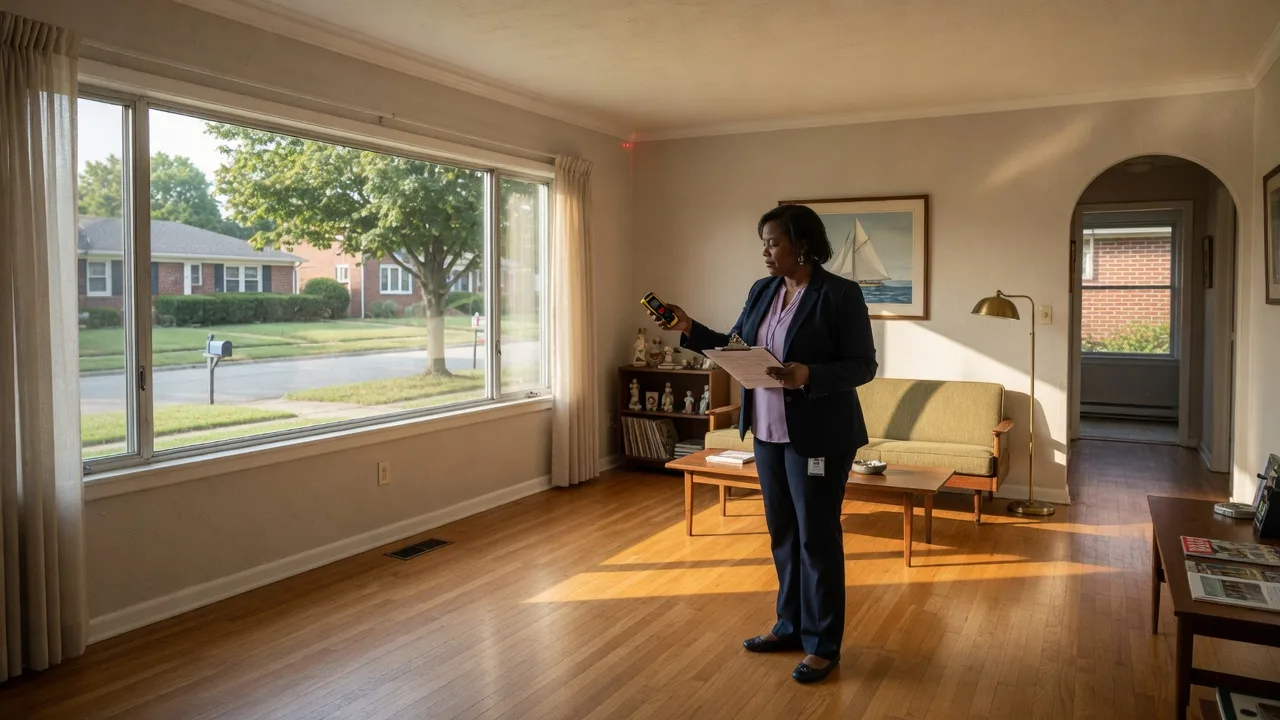
A home appraisal can make or break a real estate transaction. It is the independent valuation that tells your lender the property is worth what you agreed to pay, and in a shifting market like Dayton's in 2026, understanding how appraisals work is critical for both buyers and sellers. Here is everything you need to know, with local numbers and practical strategies.
What is a home appraisal and why is it required?
A home appraisal is an unbiased professional estimate of a property's market value. When you finance a home purchase with a mortgage, your lender requires an appraisal to confirm the property is worth at least the loan amount. If you default, the lender needs to know the property can cover what is still owed. It protects the lender, but it protects you too, by making sure you do not overpay.
How much does a home appraisal cost in Dayton Ohio?
In the Dayton area, a standard full appraisal for a single-family home typically costs between $400 and $600. That fee covers the appraiser's site visit, comparable market analysis, and the final written report. It is paid by the buyer at closing as part of the loan costs.
If you are using a VA loan for a home near Wright-Patterson AFB, the VA sets a standard fee of $625 for a single-family appraisal in Ohio. Drive-by appraisals (exterior only) run about $100 to $150, but these are rare for purchase transactions. Most conventional and FHA loans require a full interior inspection.
What does an appraiser look for during a Dayton home appraisal?
An appraiser looks at three main things: the property's condition, its size and layout, and recent sales of comparable homes in your neighborhood. The appraiser walks through every room, takes measurements and photos, and notes any visible defects or upgrades. They then compare your home to three to five similar properties that sold in the area within the last three to six months.
For Dayton neighborhoods, an appraiser will pull comps from your specific subdivision or nearby streets. A home in Centerville's school district will be compared to other Centerville homes, not to properties in Kettering or Beavercreek. Location is the single biggest factor in value.
What is the difference between an appraisal and a home inspection?
This is one of the most common questions we hear. A home inspection evaluates the physical condition of the property: the roof, foundation, HVAC, plumbing, electrical, and structural systems. It tells you what might need repair. An appraisal tells you what the property is worth in dollars. You need both. The inspection protects your wallet from hidden defects, and the appraisal protects you from overpaying.
What happens if the appraisal comes in lower than the purchase price?
A low appraisal is stressful but not a deal-killer. If the appraised value is below your agreed purchase price, the lender will only finance up to the appraised value. You have several options:
- Negotiate with the seller. The seller may agree to lower the price to match the appraised value. This is the most common outcome in a balanced market.
- Meet in the middle. You and the seller split the difference. If the gap is $10,000, you each contribute $5,000.
- Bring extra cash. You pay the difference between appraised value and purchase price out of pocket. Your loan amount is based on the lower appraised value.
- Challenge the appraisal. Your agent can present additional comps to the appraiser's lender for review. It does not always work, but it is worth the conversation.
In competitive markets, some buyers include an appraisal gap clause in their offer, agreeing to cover a certain amount above appraised value. This makes your offer stronger without waiving the appraisal entirely.
Can you skip the appraisal as a buyer?
If you are paying cash, then no appraisal is required. If you are financing, the lender generally requires one. However, recent regulatory changes raised the no-appraisal threshold for certain loans to $400,000, meaning some homes under that price may qualify for a waiver if enough data is available. Your lender can tell you whether your loan qualifies.
The Bottom Line
A home appraisal is a standard, essential part of buying or selling a home in Dayton. Understanding how it works, what it costs, and your options if the number comes in low means you can move through the process with confidence instead of scrambling at the table. Your Glasshouse agent will guide you through every step and help you navigate any appraisal situation that comes up.
Frequently Asked Questions
How long does a home appraisal take in Dayton Ohio?
The appraiser's site visit typically takes 30 to 45 minutes for a standard single-family home. The full report is usually delivered within 3 to 5 business days after the visit. In a competitive market, you may be able to request a rush delivery for an additional fee.
Who pays for the appraisal: the buyer or the seller?
The buyer typically pays the appraisal fee as part of their closing costs. The seller pays if they commission an appraisal before listing to help determine an asking price. In some cases, buyers may be asked to pay the fee upfront (before closing) so the lender can order the appraisal promptly.
Can a seller prepare for a home appraisal?
Yes. A clean, well-maintained home tends to appraise better. Make sure the home is clean, clutter-free, and that all major systems (HVAC, water heater, roof) are in good working order. Provide the appraiser with a list of recent upgrades and improvements with dates and costs. This can help justify a higher value compared to homes without those updates.
Published August 24, 2026 · Updated August 24, 2026
Have questions about the appraisal process?
We walk buyers and sellers through appraisals every day. We are happy to answer your questions and help you prepare.
Talk to an AgentWondering how an appraisal affects your transaction?
We can help you understand what to expect and how to prepare, whether you are buying or selling in the Dayton area.
No pressure. Just clear, honest answers from people who handle appraisals daily.
Schedule a Consultation